DeFi — decentralized finance — is a set of financial services rebuilt as public smart contracts, so that trading, lending, borrowing and holding a dollar-pegged token happen without a bank, broker or exchange sitting in the middle. The rules live in code anyone can read, the contracts execute automatically, and you keep custody of your assets the entire time.
That last clause is the whole trade. You gain access without permission and rules you can verify; you give up the refund desk, the frozen-transaction reversal and the deposit guarantee. Below is what each DeFi primitive actually does, where its yield comes from, and the specific ways people lose money in it.
What DeFi replaces, service by service
The clearest way to understand DeFi is not as a new invention but as a re-implementation. Almost every piece maps onto something a bank already does — with a different failure mode attached.
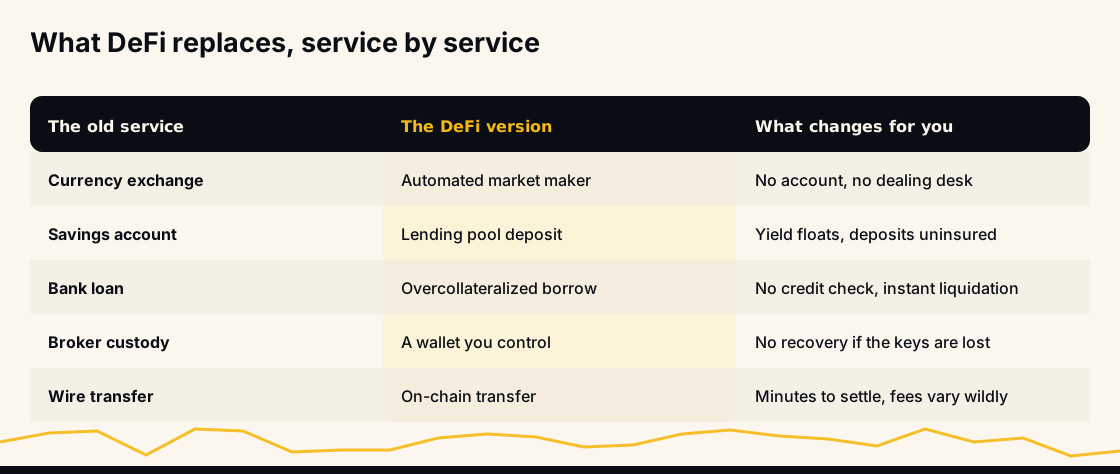
Notice the right-hand column. Every gain in access is paid for with the loss of an intermediary who used to absorb a specific risk on your behalf. That is not an argument against DeFi; it is the thing you are actually deciding about.
The one ingredient that made it possible
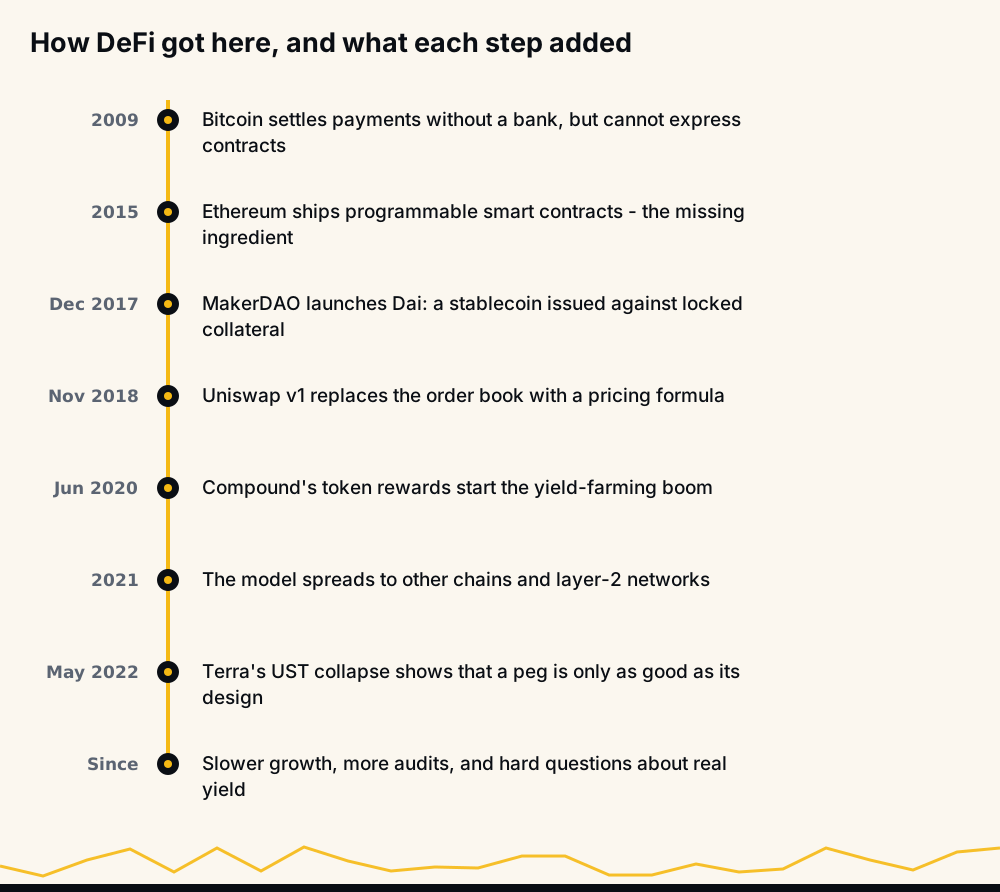
Bitcoin proved in 2009 that value could move without a bank, but its scripting was deliberately limited — you cannot express a loan agreement in it. Ethereum's smart contracts in 2015 supplied the missing piece: programs that hold funds and release them only when stated conditions are met, with no ability for anyone to intervene.
A lending contract can therefore accept collateral, track a debt, and sell that collateral automatically when it becomes insufficient, without anyone deciding to do it. The contract does not know who you are and cannot be persuaded.
How a decentralized exchange works without an order book
Traditional exchanges match buyers to sellers. Most DEXs do something stranger: a pool holds two tokens, and a formula prices trades so that the product of the two balances stays constant. Buy more of one token and its price rises along a curve. No counterparty is needed — you trade against the pool.
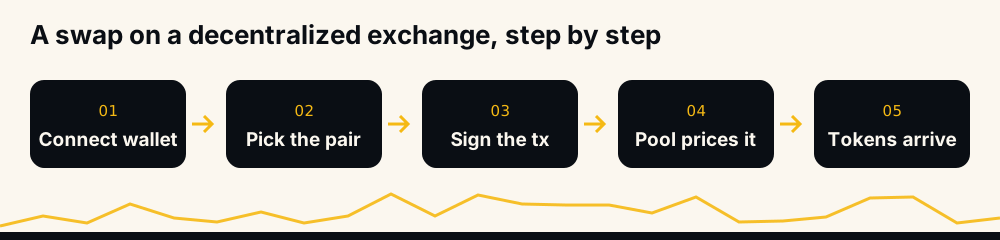
Two consequences follow immediately. Large trades move the price against you — slippage is structural, not a fee. And thin pools are dangerous to trade in for exactly the same reason. Anyone comparing venues should read how spot and futures markets differ for small accounts before assuming a DEX price is the market price.
Lending without a credit check
DeFi lending has no underwriting because it has no identity. It solves the same problem with collateral: to borrow 100 in stablecoins, you lock more than 100 in another asset. If your collateral falls in value past a threshold, anyone can trigger a liquidation and take a fee for doing it.
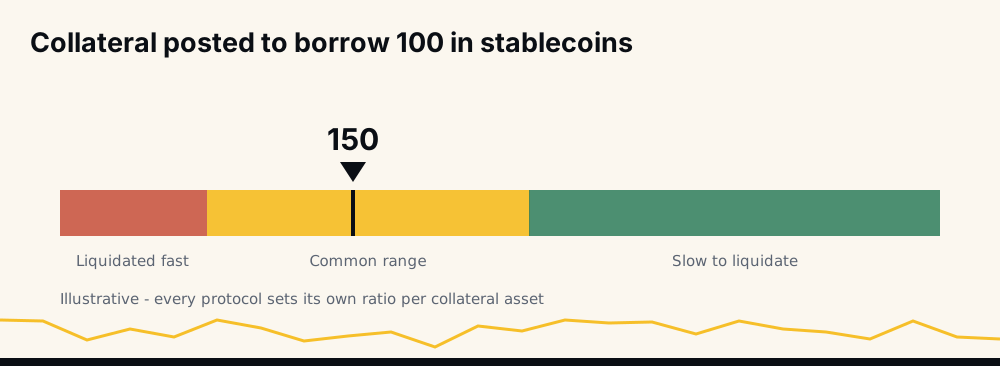
This is why DeFi loans are not a consumer credit product. Nobody borrows to buy a car; they borrow to get liquidity without selling a position, and they get liquidated when the market moves faster than they can top up. Liquidation is not a penalty for being late — it is instant, automated and indifferent.
Stablecoins: the unit everything is priced in
DeFi runs on dollar-pegged tokens, and that is worth pausing over. A system built to route around traditional currency adopted the dollar as its unit of account within a few years, because nobody wants to owe a debt denominated in something that can double overnight.
There are two broad designs: reserve-backed tokens, where an issuer claims to hold dollars or short-term assets against each token, and collateral-backed tokens minted on-chain against locked crypto. The first asks you to trust an issuer's reserves; the second asks you to trust a mechanism under stress. Terra's UST in May 2022 demonstrated what happens when the mechanism is the peg and confidence goes.
Liquidity pools, and where the yield actually comes from
If you supply both tokens to a pool, you receive LP tokens representing your share and you earn a cut of trading fees. Protocols often add their own token on top as an incentive. This is where advertised percentages come from, and where most misunderstanding lives.
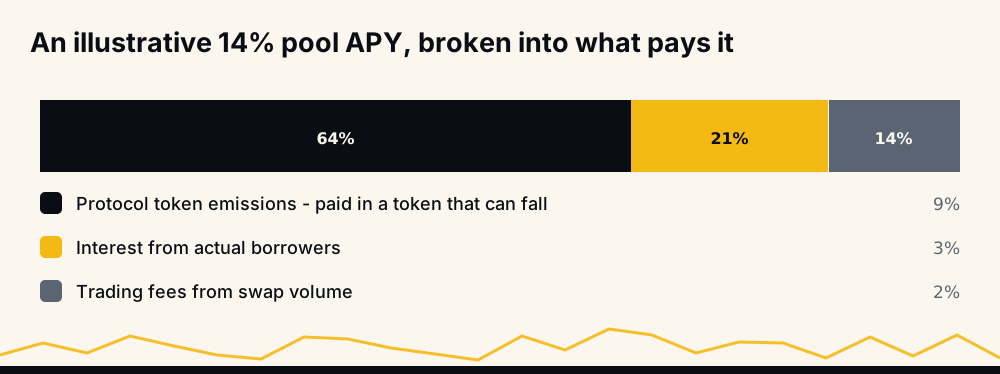
Break any headline yield into its parts. Fee income and borrower interest are real revenue paid by real users. Emissions are a token being printed and handed to you — if everyone earning it sells it, the yield you were quoted is not the yield you receive. Evaluating those tokens is the same problem as evaluating any coin, and the five-step approach to judging a cryptocurrency's value applies here directly.
Impermanent loss, with actual numbers
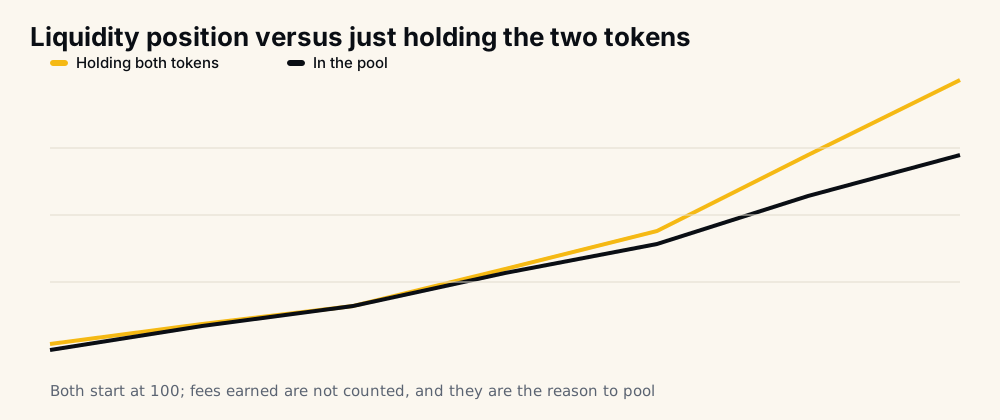
Supplying a pool is not the same as holding the two tokens. As their relative price moves, the pool automatically sells the rising asset and buys the falling one. The gap between your pool position and simply having held is called impermanent loss, and it is only impermanent if the price comes back.
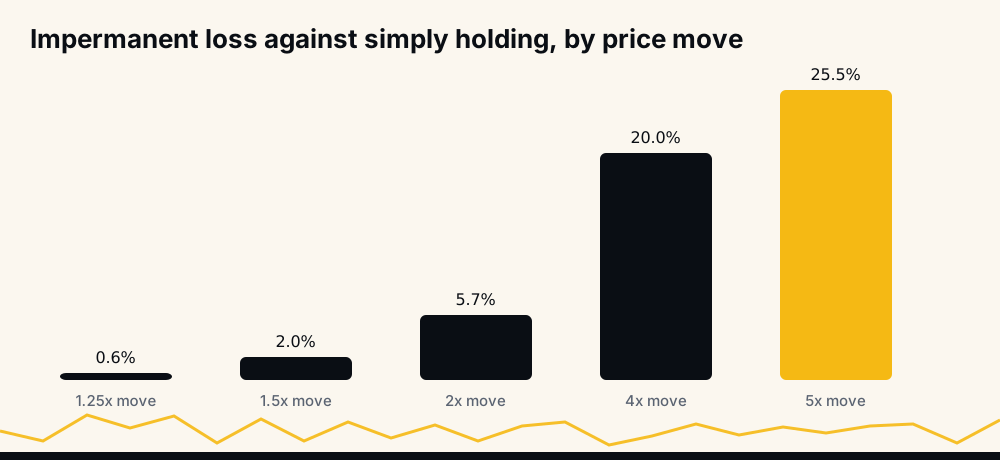
The figures follow from the pool formula, so you can check them: a doubling in one token's relative price costs about 5.7% versus holding, a 4x costs 20%. Fees have to exceed that gap for the position to have been worth taking.
Composability: why the pieces snap together
The property that makes DeFi more than a set of websites is composability. Every contract is a public interface, so one protocol can call another without asking permission or signing an agreement. A single transaction can borrow, swap, deposit and repay across four different applications and revert entirely if any step fails.
That is why people call these applications money legos, and it is genuinely new — no bank lets a rival's software reach into its ledger mid-transaction. It is also why the risk profile is unusual. Composability means the failure of one widely used contract propagates into everything built on top of it, and a protocol you never used can still be the reason your position was liquidated. Interconnection is the feature and the systemic risk in the same sentence.
The risks nobody puts in the brochure
Each of these has cost people real money, repeatedly:
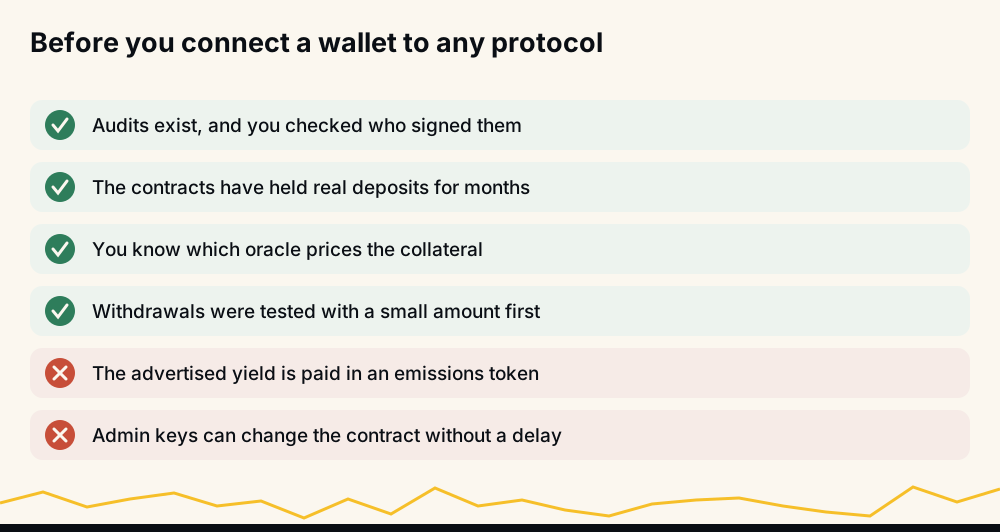
- Smart contract bugs. The code is the bank. A logic error in a contract holding pooled deposits can drain all of them in a single transaction, and audits reduce that risk without eliminating it.
- Oracle manipulation. Contracts learn prices from oracles. If an attacker can move the price an oracle reports — often with a flash loan, borrowed and repaid inside one transaction — they can borrow against collateral that is not worth what the protocol thinks.
- Rug pulls. A team launches a token, seeds a pool, attracts deposits, then removes the liquidity or mints itself an unlimited supply. Retained admin keys and unlocked liquidity are the tells.
- Governance capture. If tokens control the contract's parameters, buying enough of them can be cheaper than hacking the code.
- Bridge failures. Moving assets between chains concentrates enormous value in one contract, and bridges have been among the largest exploits in the sector.
- Your own execution. Wrong network, wrong contract address, unlimited spending approvals left open from a year ago. This category is boring and extremely common.
DeFi versus CeFi: what each one asks you to accept
CeFi means centralized finance — exchanges, brokers and custodial lenders. The honest comparison is not "trustless versus trusted" but "which risks do you prefer".
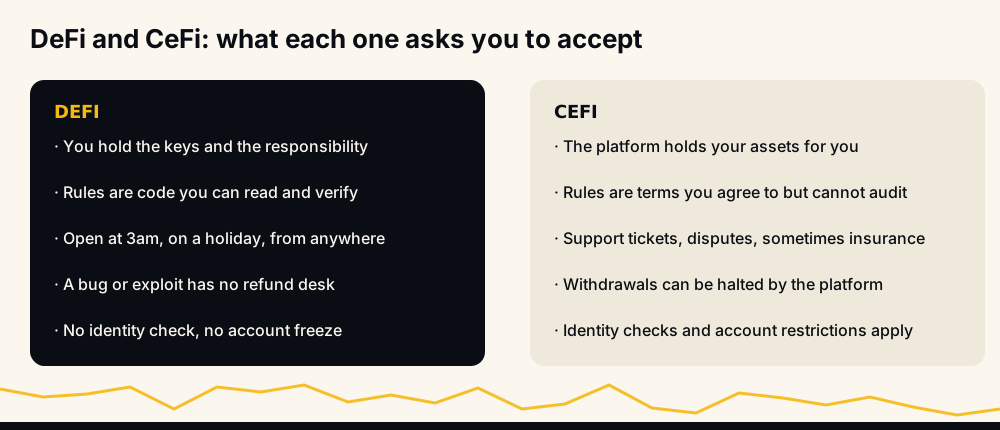
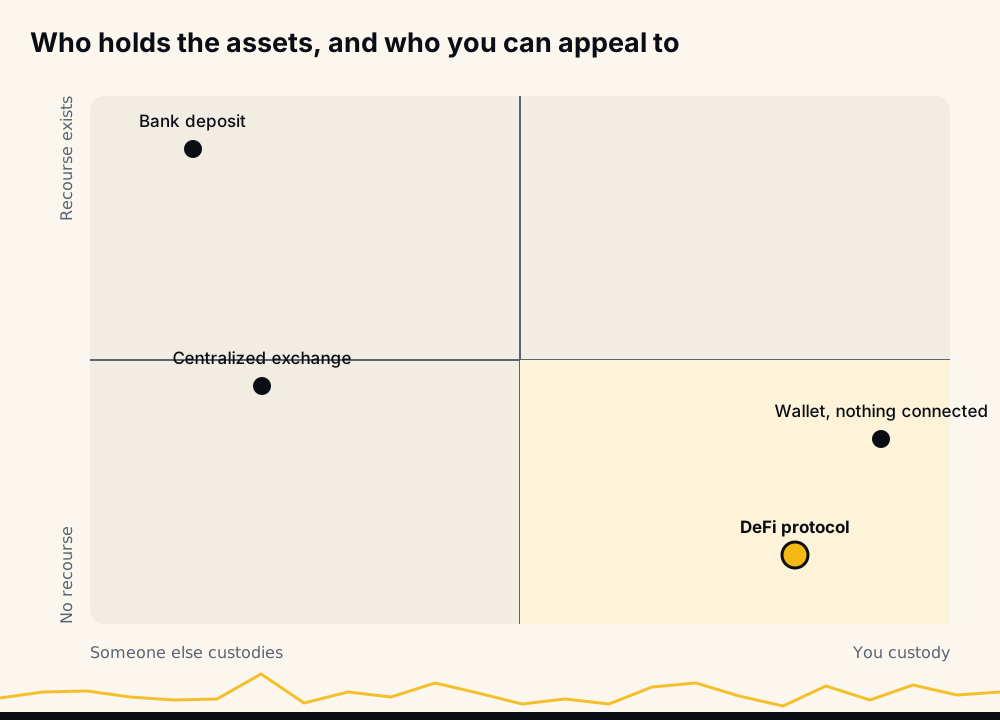
CeFi platforms have failed catastrophically too, and their users had no recourse worth having when they did. The difference is that DeFi's risk is visible in advance and CeFi's tends to become visible on the day withdrawals stop.
Who DeFi is genuinely useful for
Two groups, and it is worth being precise because the marketing is not.
The first is people underserved by conventional banking — those without documentation a bank will accept, in countries with capital controls, or with an unstable domestic currency. For them a stablecoin wallet is not an ideology; it is the first savings instrument that does not lose a fifth of its value every year. That is the strongest case DeFi has, and it gets buried under yield-farming content.
The second is traders and treasuries who want to borrow against a position without selling it, move collateral at 3am, or price liquidity without asking a desk. Everyone else is usually there for the yield, and yield is where the losses cluster. Understanding why humans make poor trading decisions under pressure explains a lot of DeFi's casualty list better than any technical account does.
What DeFi does not solve
It does not tell you what to buy. A protocol will lend against a position that is about to be liquidated with exactly the same enthusiasm as one that is not, because it holds no opinion about direction.
That is the gap tools like ours address, and we are careful about the claim. HafizeBot produces AI-generated signals from a model that evaluates 240+ indicators, formulas and components across 500+ Binance USDT-M perpetual pairs, rating each signal by strength. It is a research and execution aid on centralized futures markets, not a DeFi product, and it does not remove the risks described above — it just gives you a documented basis for a directional decision instead of a hunch. The broader case for handing that work to software is in why algorithmic trading keeps drawing interest.
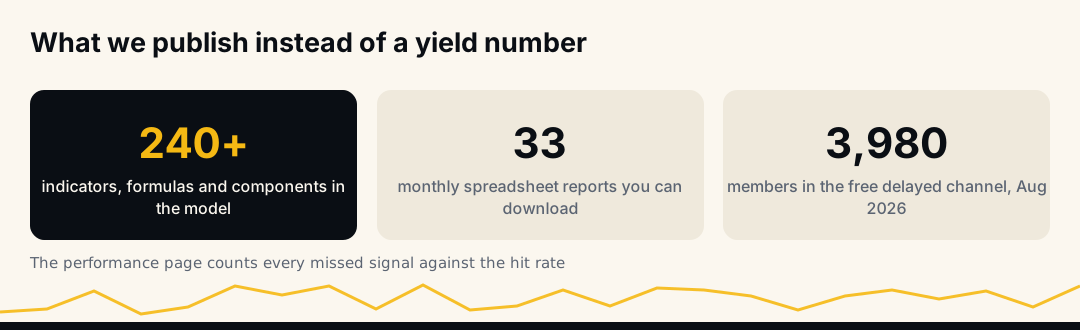
The archive is 33 monthly spreadsheet reports covering June 2021 to February 2024 and 33,694 signals, with median monthly accuracy of 98.9% as reported in those spreadsheets, downloadable from the reports page. Since June 2026 the live performance page has been rebuilt hourly from the trade database, where a win is a target hit, and the page shows Wins, Missed and Open. Broadcast signals carry a target and a maximum hold, not a stop, so every signal that does not reach its target in time counts as Missed and lowers the rate. Losing months show up as losing months.
Frequently asked questions
Is DeFi the same as crypto? No. Crypto is the asset class; DeFi is a category of applications built on top of some of those assets. You can own bitcoin for years and never touch a DeFi protocol, and most DeFi activity happens on smart-contract chains rather than on Bitcoin itself.
Is DeFi safe? It is safe from some risks and badly exposed to others. Nobody can freeze your account or lose your deposit through their own insolvency, but a contract bug, an oracle exploit or a mistaken approval can take everything with no recovery path. Treat it as high-risk software, not as a savings account.
How do you actually make money in DeFi? Three legitimate sources: interest paid by borrowers, fees paid by traders, and protocol token emissions. The first two are revenue somebody actually generated. The third is a token being issued, and its value depends entirely on whether demand for that token holds up once the emissions stop.
What is impermanent loss in simple terms? When you supply two tokens to a pool and their relative price changes, the pool rebalances you into more of the weaker asset. If you withdraw at that point you hold less value than if you had simply kept both tokens. A doubling in one token's relative price costs roughly 5.7% versus holding, before any fees you earned.
Do I need a DeFi wallet to trade crypto signals? No. Signal trading described on this site happens on centralized futures markets through exchange API keys, not through DeFi protocols. The two are separate activities with separate risks.
What is the difference between DeFi and CeFi? Custody and recourse. In CeFi a company holds your assets and you have a support channel and sometimes legal protection; in DeFi you hold your own assets and the code is the only authority. Both have lost users large amounts of money, in different ways.
Where to go from here
If you are exploring DeFi, start by moving an amount you would shrug at, complete a full round trip including the withdrawal, and read the contract's audit before you read its APY. If you are here for directional trading instead, the free channel at t.me/getbinancefutures carries the calls of strength 3 and up on a twenty-minute delay and had roughly 3,980 members in August 2026 — enough to watch how signals behave for a few weeks before anything is at stake. Autotrading, for those who go that far, needs API keys with trading permission only, never withdrawal permission; funds stay on the user's own Binance account, and the user sets the minimum signal strength, position size, maximum simultaneous positions and coin filters.
None of this is investment advice, and no part of it promises a profit. Smart contracts fail, pegs break, signals lose, and the people who survive both DeFi and trading are the ones who sized for that in advance. Trade only what you can afford to lose.